Saturday , October 3, 2026 |   05:36:07 IST
INTL TAXATION INTL MISC TP FDI LIBRARY VISA BIPA NRI
About Us Contact Us Newsletters
 
NEWS FLASH
 
I-T - Allocation of IT costs & management expenses by Indian branch to its foreign head office is not taxable as FTS in India: ITAT (See Breaking News) I-T-Payment cannot be deemed to be royalty where it is consideration for services involving managerial & technical inputs, not involving any transfer of technical knowledge & not satisfying Make Available test: ITAT (See Breaking News) I-T - Final assessment order passed u/s 143(3) and 144C(13) after expiry of outer time limit u/s 153 is barred by limitation: ITAT (See Breaking News) TOLA 2026 - (Part-2): A dazzling future for the diamond sector in India? (See TII EDIT) TP - Resale Price Method is ordinarily most appropriate method where goods are purchased from an AE and resold to unrelated parties without value addition: ITAT (See Breaking News) I-T - Special circumstances u/s 119(2) for condonation of delay cannot be confined in predefined formula or limited expression: HC (See Breaking News) TP - Segmental profitability cannot be summarily discarded solely due to profit variances between AE & non-AE segments: ITAT (See Breaking News) TP - No separate ALP adjustment for delayed receivables is warranted if TNMM with working capital adjustment already covers impact: ITAT (See Breaking News) TP - Per Section 144C, AO is statutorily bound to follow directions of DRP & omission to pass final order in conformity with DRP's directions invalidates such order: ITAT (See Breaking News) INTL - Per settled legal position, date on which document or order is electronically uploaded on ITBA portal with generated DIN must be legally recognized as date of receipt by tax authority: ITAT (See Breaking News) I-T - Section 149(1)(c) applies equally to non-residents and absence of foreign asset disclosure obligation does not bar reopening: ITAT SB (See Breaking News) TP - As per settled precedent, Bright Line Test method is rejected for determining adjustments on Advertising Marketing and Promotion expenses: ITAT (See Breaking News) I-T - Revenue cannot treat Sec 144C as standalone code to bypass limitation period u/s 153: ITAT (See Breaking News) TP - Per Section 144C, AO is required to first pass draft assessment order, if adjustment prejudicial to assessee is proposed, before passing the final order: ITAT (See Breaking News) TP - Rejection of TNMM method adopted by assessee without bringing any comparable uncontrolled transaction on record & determination of ALP on ad hoc basis is sustainable: ITAT (See Breaking News) INTL - PCIT, being an authority of coordinate rank, is not empowered to invoke revisional jurisdiction u/s 263 over assessment framed in compliance with DRP's directions: ITAT (See Breaking News) INTL - DRP is collegiate body & holds coordinate rank with PCIT; ergo, order passed per directions of DRP cannot be subject to revision u/s 263: ITAT (See Breaking News) TP - TPO ought to apply 10-times turnover filter on either side of assessee's turnover, considering that size of operations in software sector has bearing on operating margins & that large companies enjoy advantages arising from operational efficiencies & intangibles: ITAT (See Breaking News)
 
TII SEARCH


Home >>
 

Income-tax (Ninth Amendment) Rules, 2023 - CBDT amends scheme & prescribes new Form 34C & 34D & 34DA & 34E
By TII News Service
Jun 12, 2023 , New Delhi


[TO BE PUBLISHED IN THE GAZETTE OF INDIA, EXTRAORDINARY, PART II, SECTION 3, SUB-SECTION (ii)]

GOVERNMENT OF INDIA
MINISTRY OF FINANCE
DEPARTMENT OF REVENUE
CENTRAL BOARD OF DIRECT TAXES
NEW DELHI

NOTIFICATION NO

37/2023, Dated: June 12, 2023

G.S.R. 432(E).- In exercise of the powers conferred by section 245Q read with section 295 of the Incometax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend Income-tax Rules, 1962, namely: --

1. Short title and commencement.-- (1) These rules may be called the Income-tax (Ninth Amendment) Rules, 2023.

(2) They shall come into force from the date of their publication in the Official Gazette.

2. In the Income-tax Rules, 1962, (hereinafter referred to as the said rules), in rule 44E, for sub-rule (2), the following sub-rule shall be substituted, namely:-

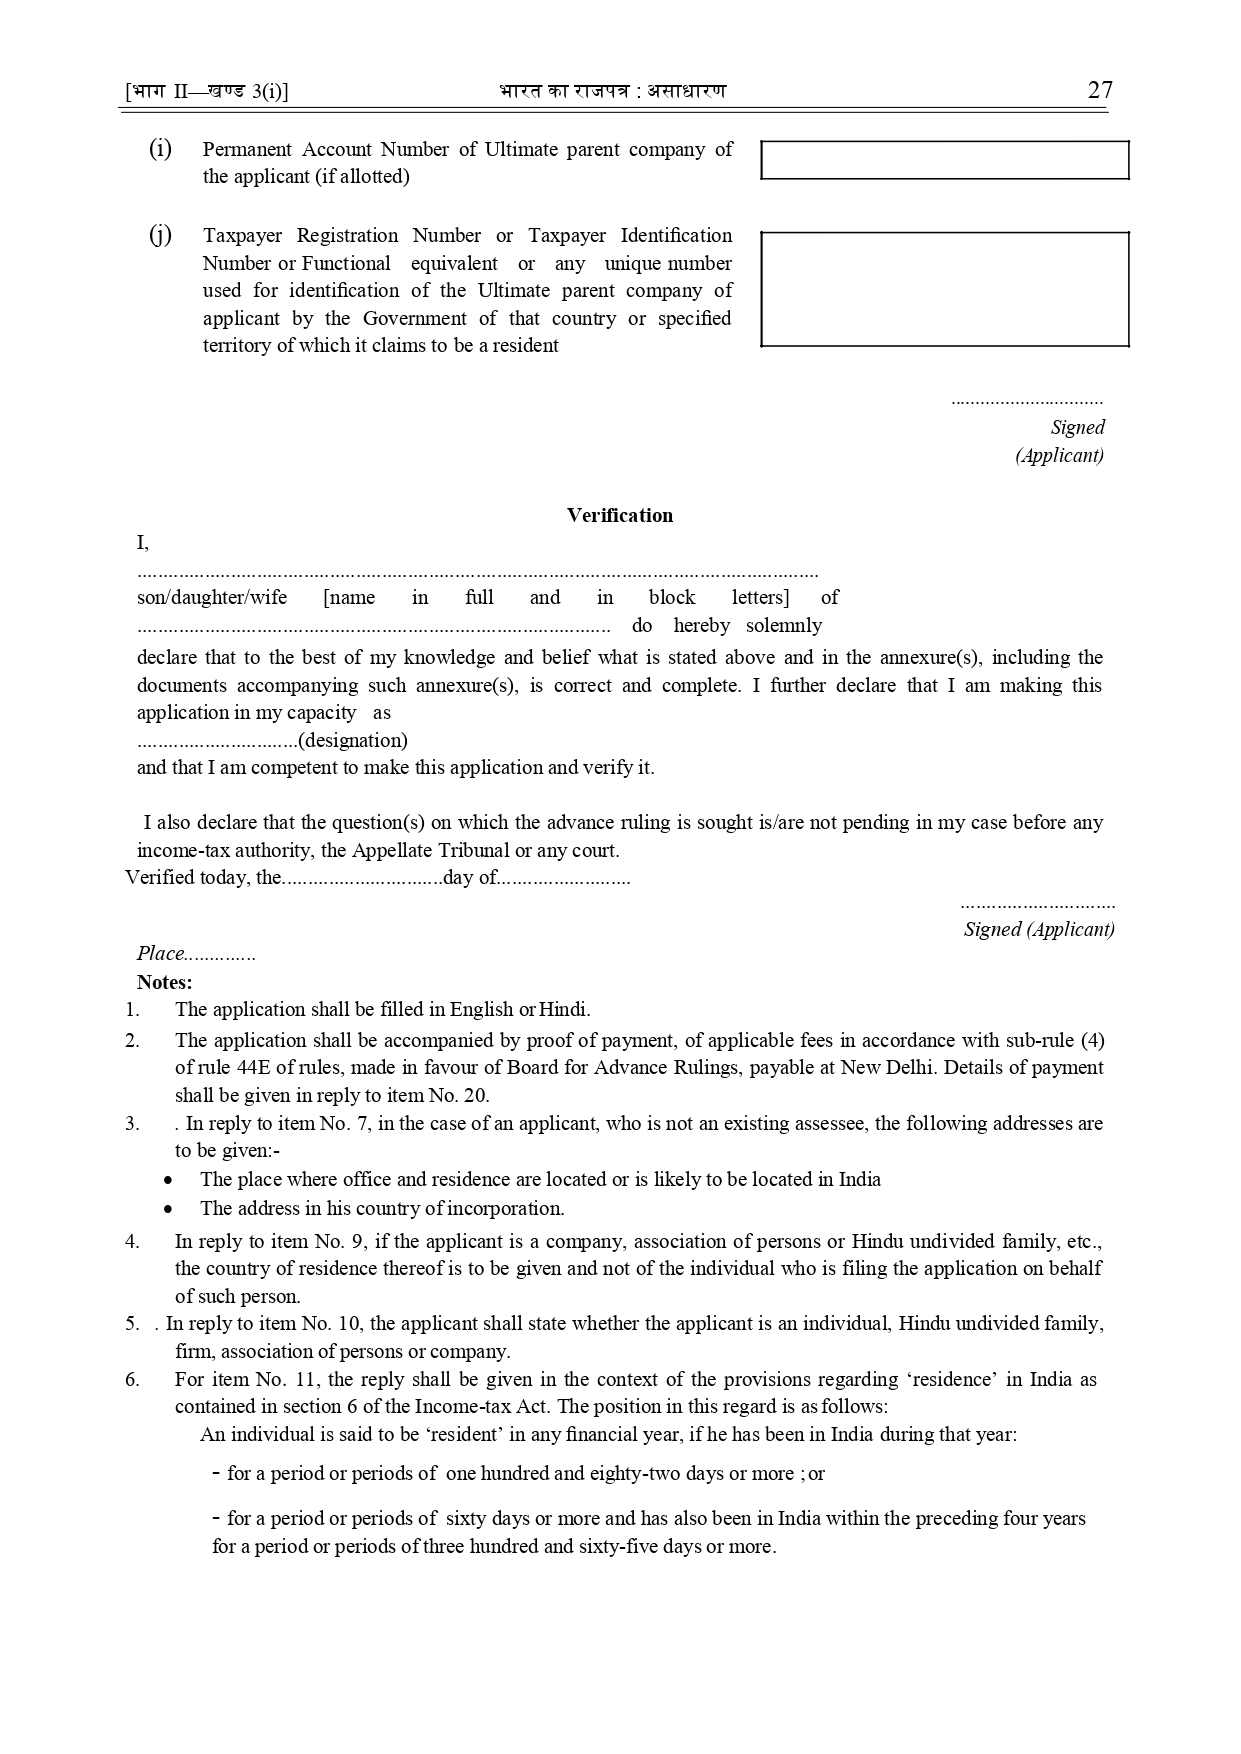
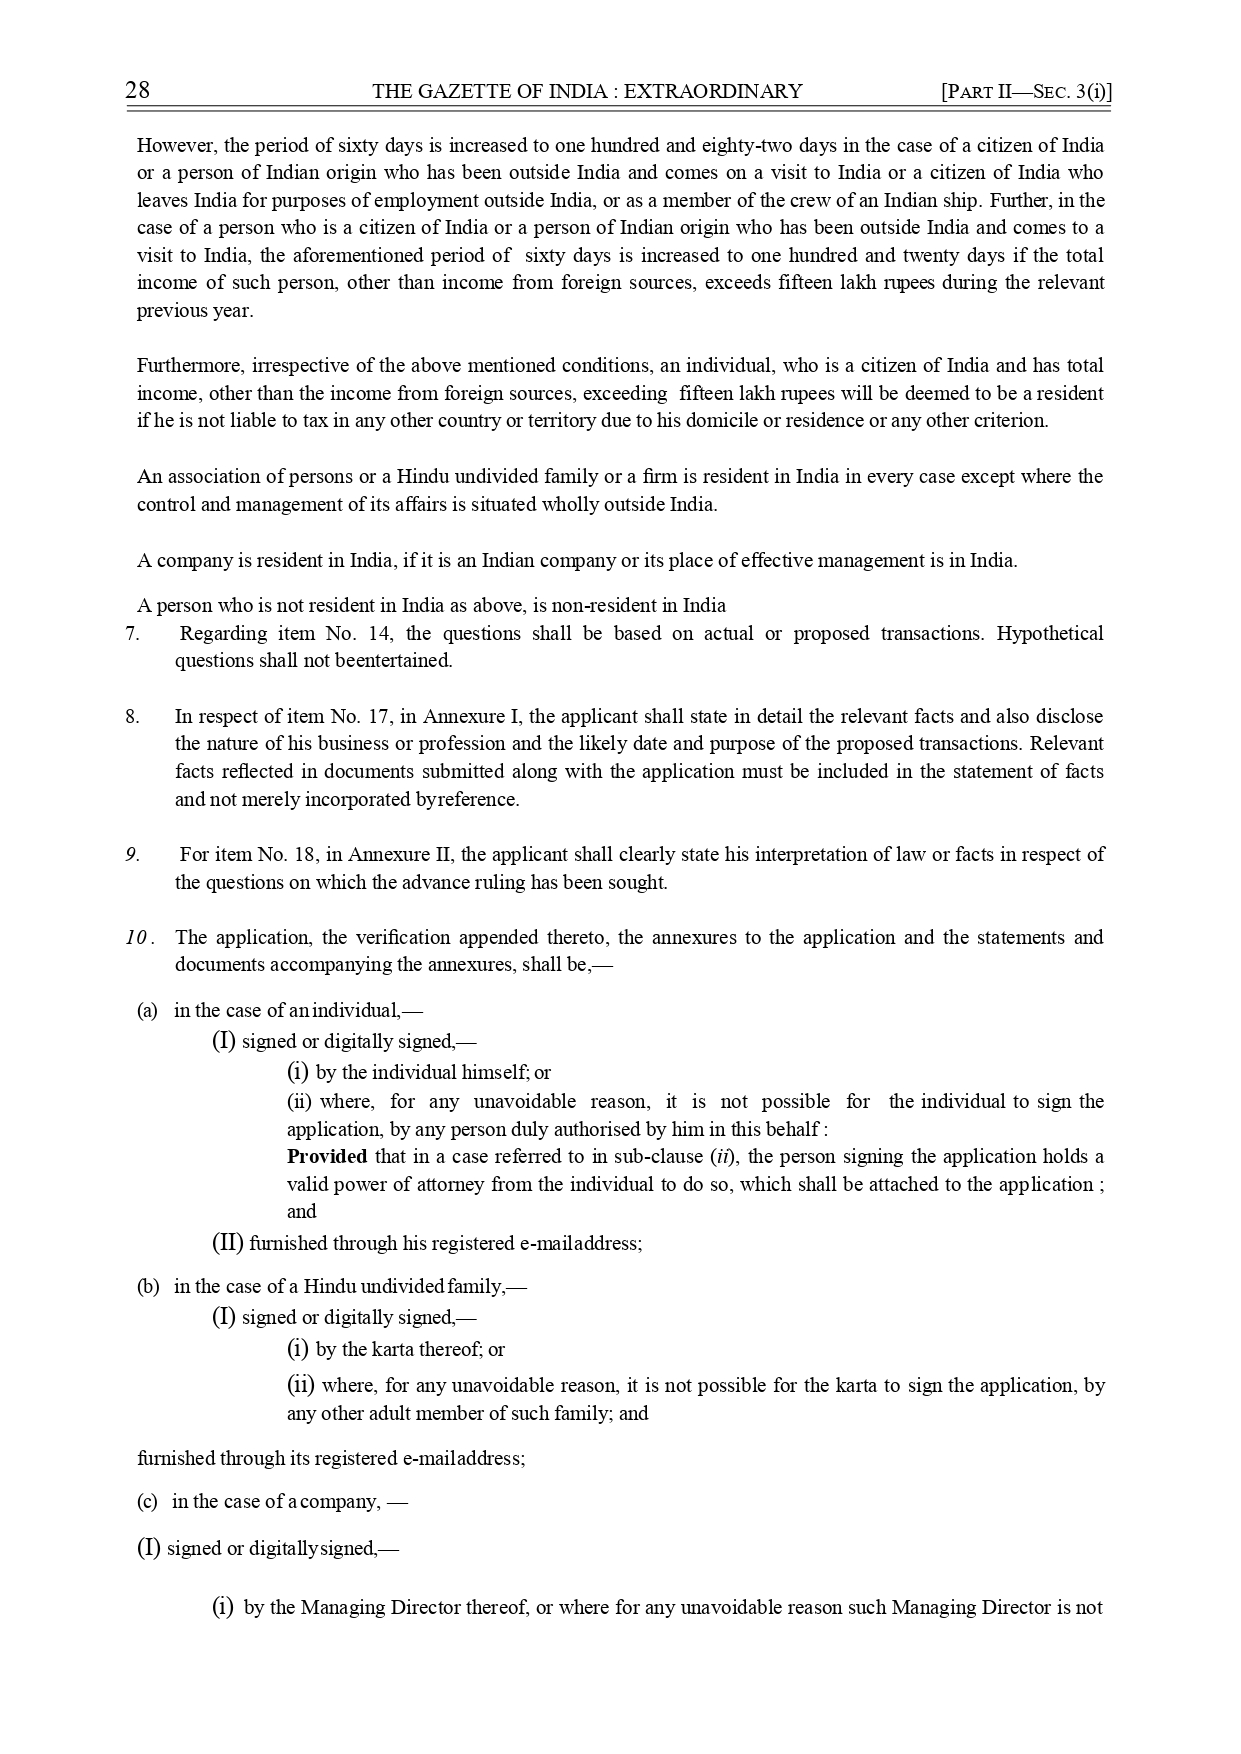
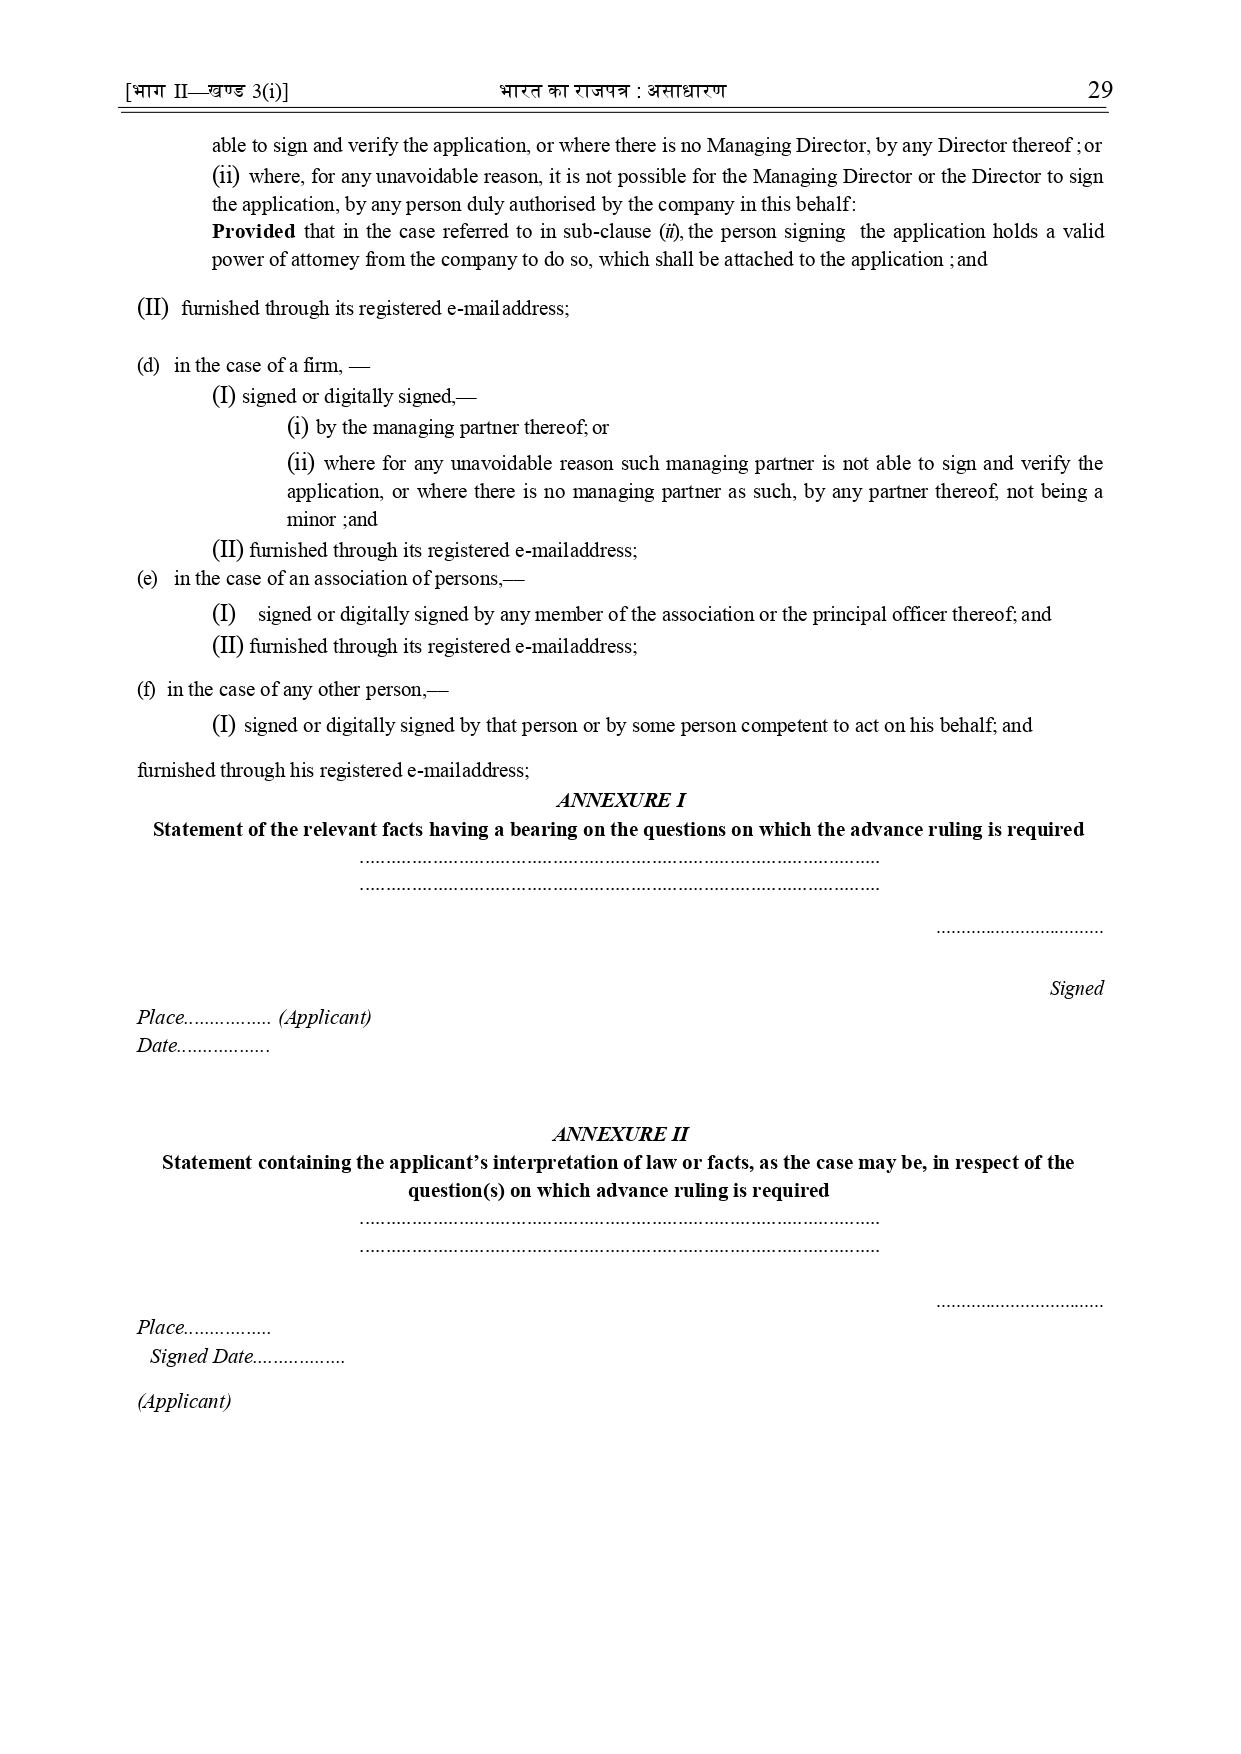
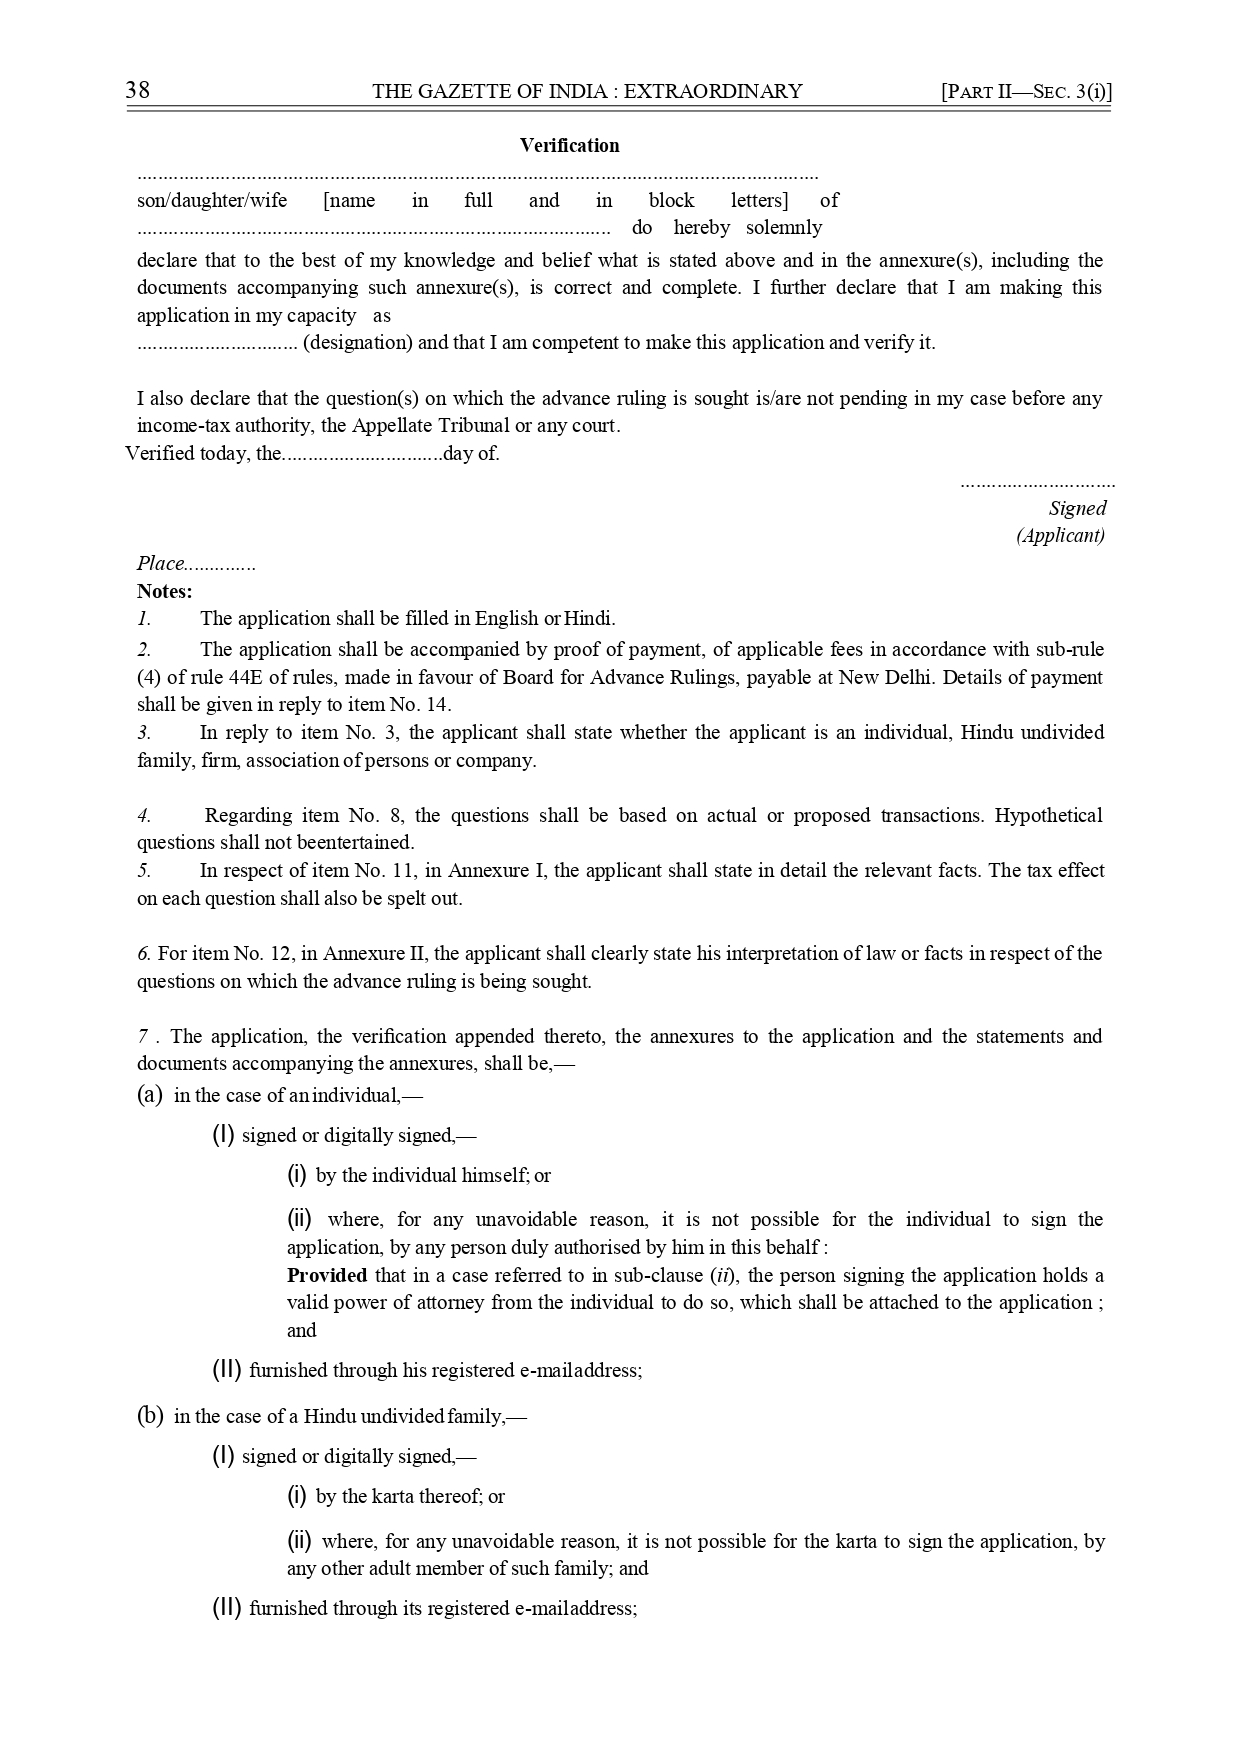
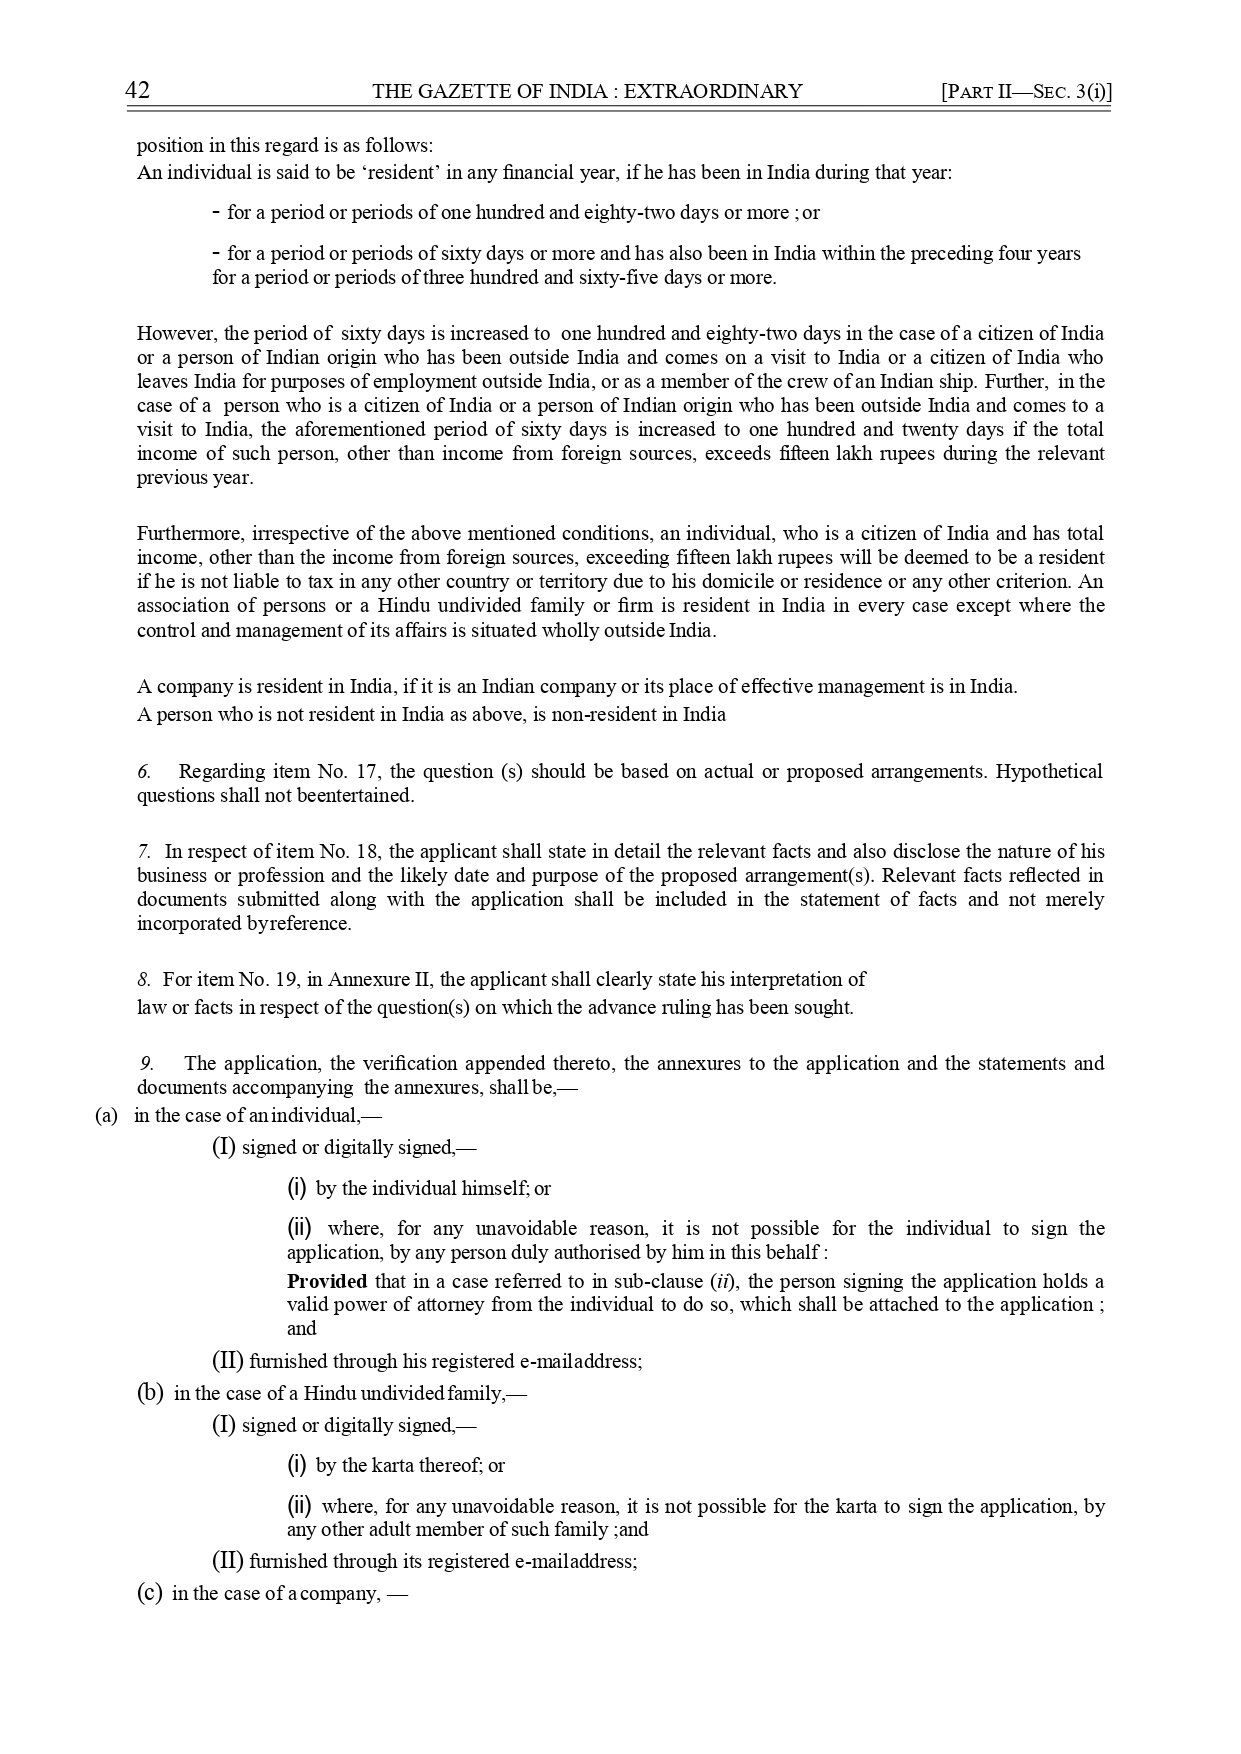
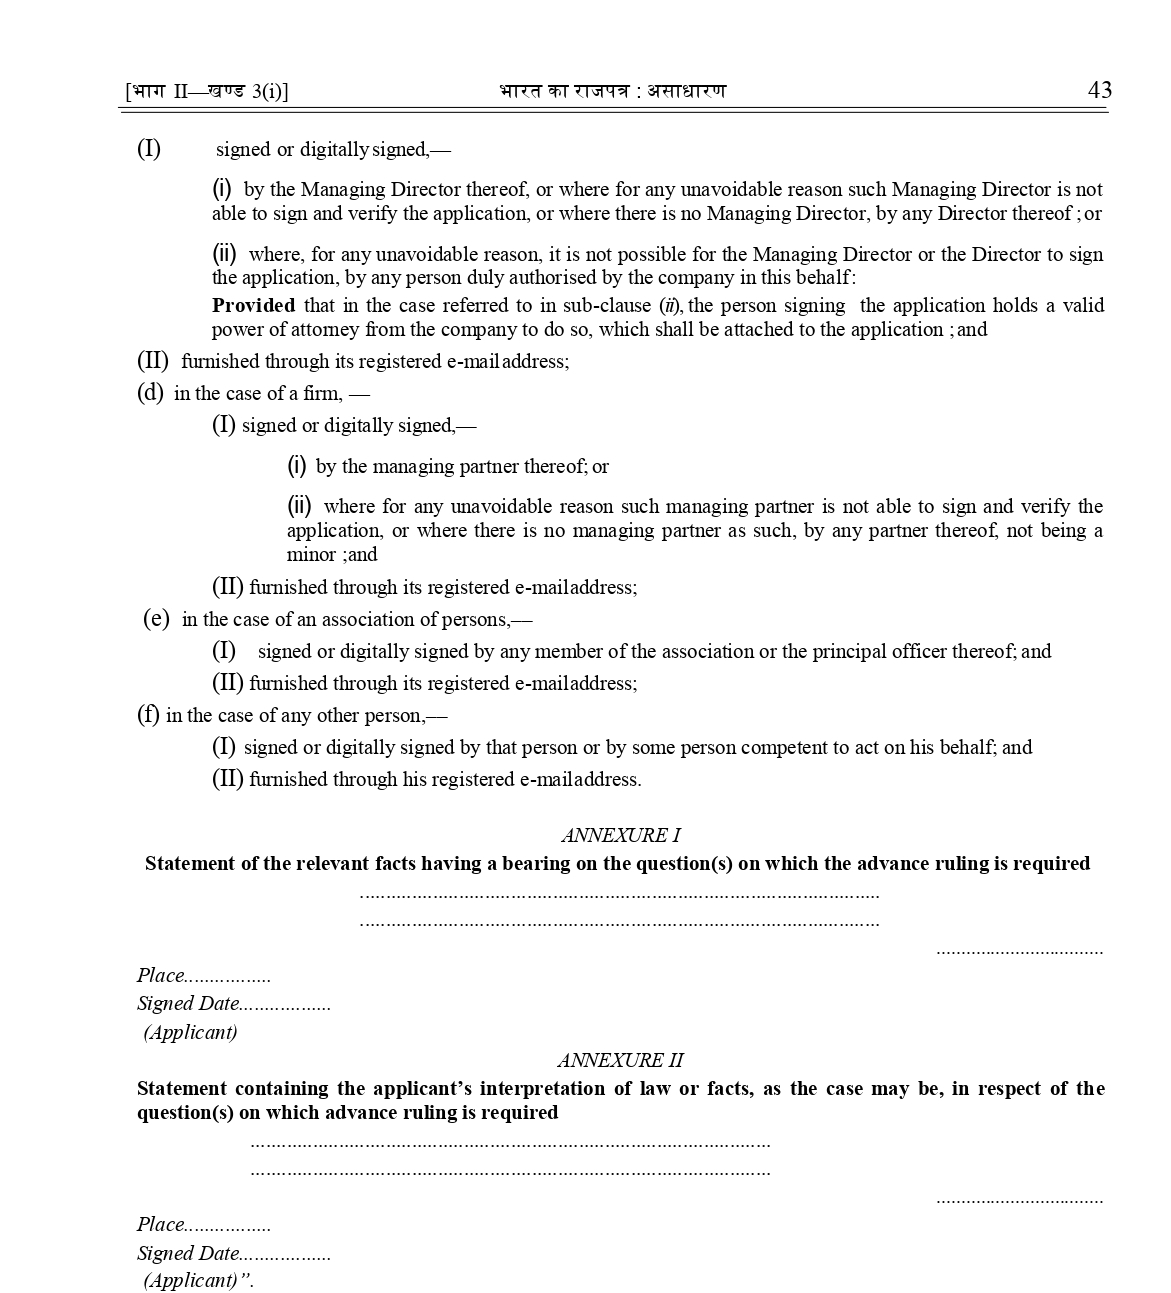
"(2) The application referred to in sub-rule (1), the verification appended thereto, the annexures to the said application and the statements and documents accompanying the annexures, shall be,- (a) in the case of an individual,-

(I) signed or digitally signed,--

(i) by the individual himself; or

(ii) where, for any unavoidable reason, it is not possible for the individual to sign the application, by any person duly authorised by him in this behalf:

Provided that in a case referred to in sub-clause (ii), the person signing the application holds a valid power of attorney from the individual to do so, which shall be attached to the application; and

(II) furnished through his registered e-mail address;

(b) in the case of a Hindu undivided family,-

(I) signed or digitally signed,--

(i) by the karta thereof; or

(ii) where, for any unavoidable reason, it is not possible for the kartato sign the application, by any other adult member of such family; and

(II) furnished through its registered e-mail address;

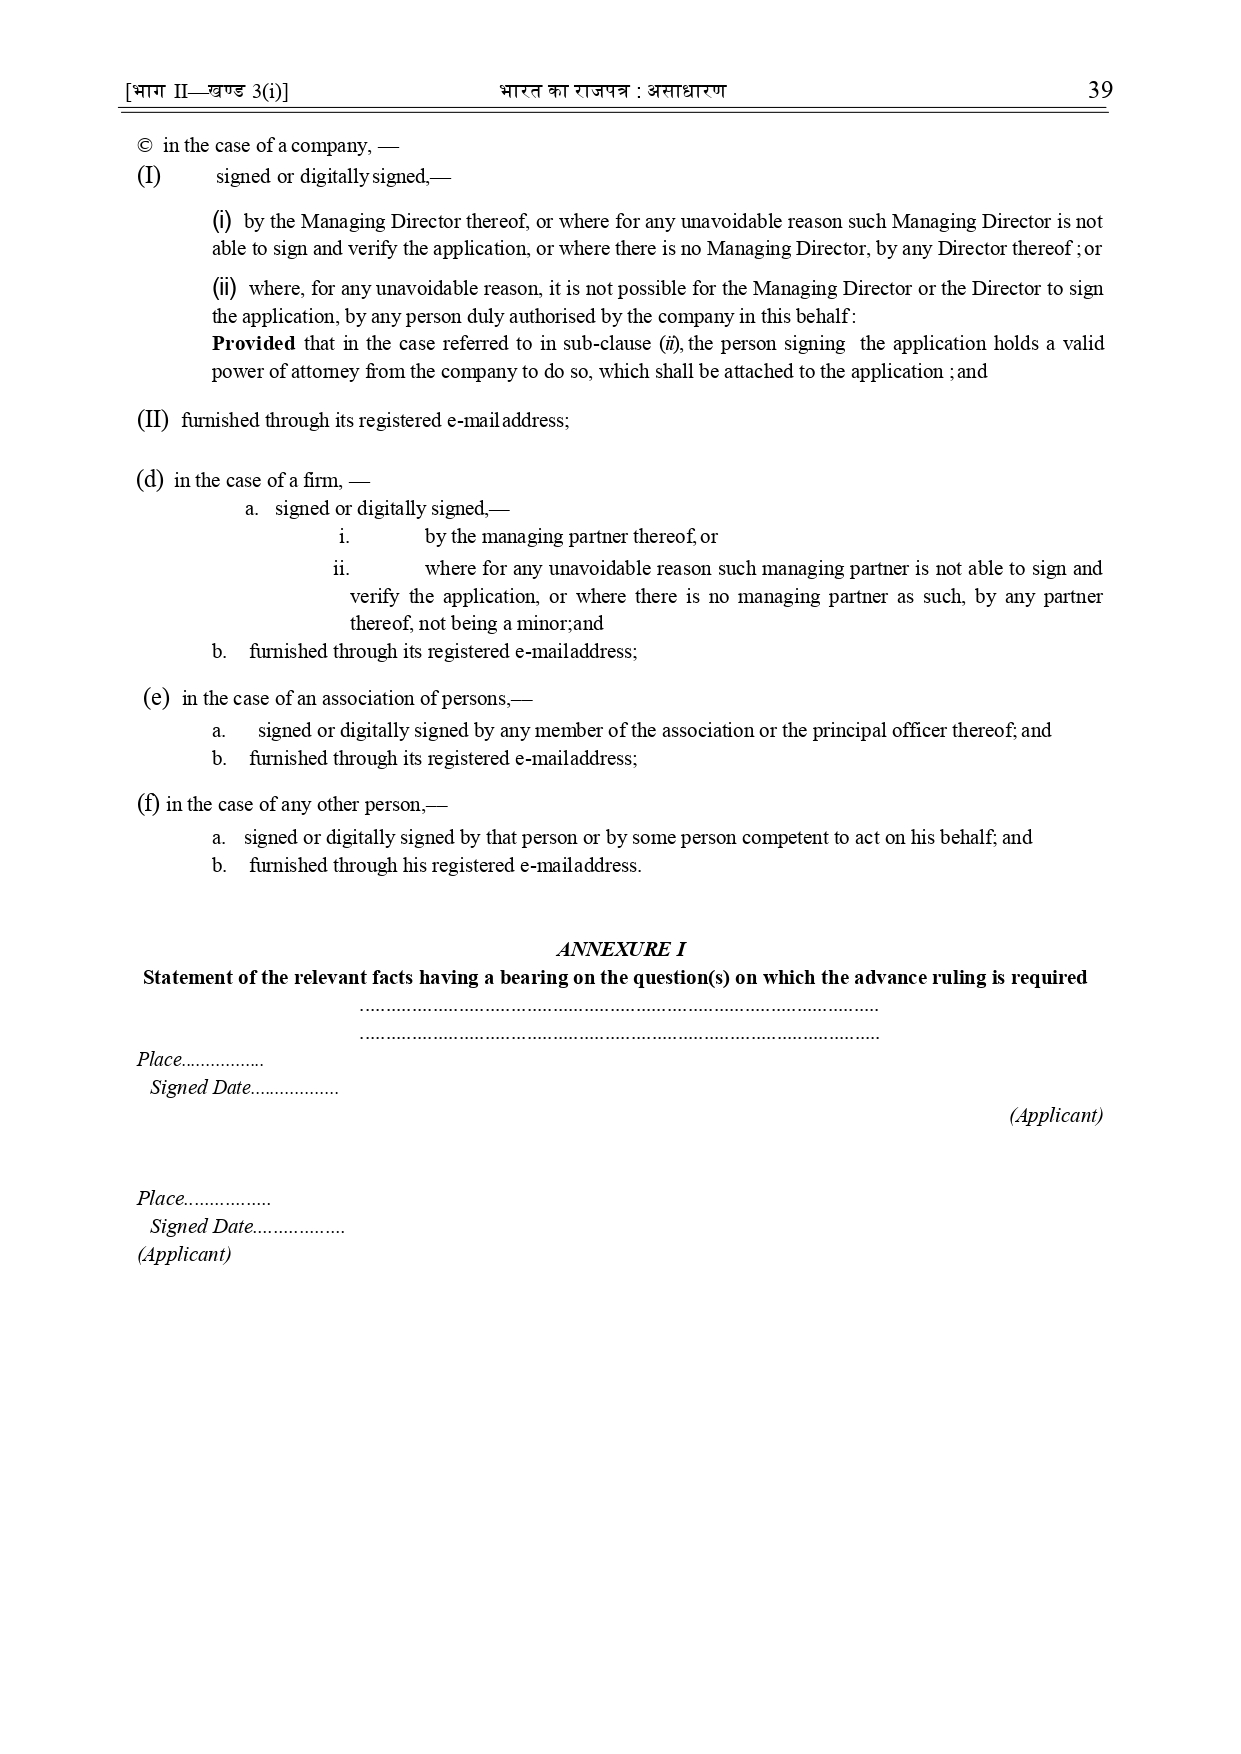
(c) in the case of a company, -

(I) signed or digitally signed,-

(i) by the Managing Director thereof; or where for any unavoidable reason such Managing Director is not able to sign and verify the application, or where there is no Managing Director, by any Director thereof; or

(ii) where, for any unavoidable reason, it is not possible for the Managing Director or the Director to sign the application, by any person duly authorised by the company in this behalf: Provided that in the case referred to in sub-clause (ii), the person signing the application holds a valid power of attorney from the company to do so, which shall be attached to the application; and

(II) furnished through its registered e-mail address;

(d) in the case of a firm, -

(I) signed or digitally signed,--

(i) by the managing partner thereof; or

(ii) where for any unavoidable reason such managing partner is not able to sign and verify the application, or where there is no managing partner as such, by any partner thereof, not being a minor; and

(II) furnished through its registered e-mail address;

(e) in the case of an association of persons,--

(I) signed or digitally signed by any member of the association or the principal officer thereof; and

(II) furnished through its registered e-mail address;

(f) in the case of any other person,--

(I) signed or digitally signed by that person or by some other person competent to act on his behalf; and

(II) furnished through his registered e-mail address.

3. In the said rules, in rule 44F,-

(i) in the marginal heading, for the word "Authority", the word "Board" shall be substituted;

(ii) for the word "Authority" at both the places where they occur, the word "Board" shall be substituted, in both places.

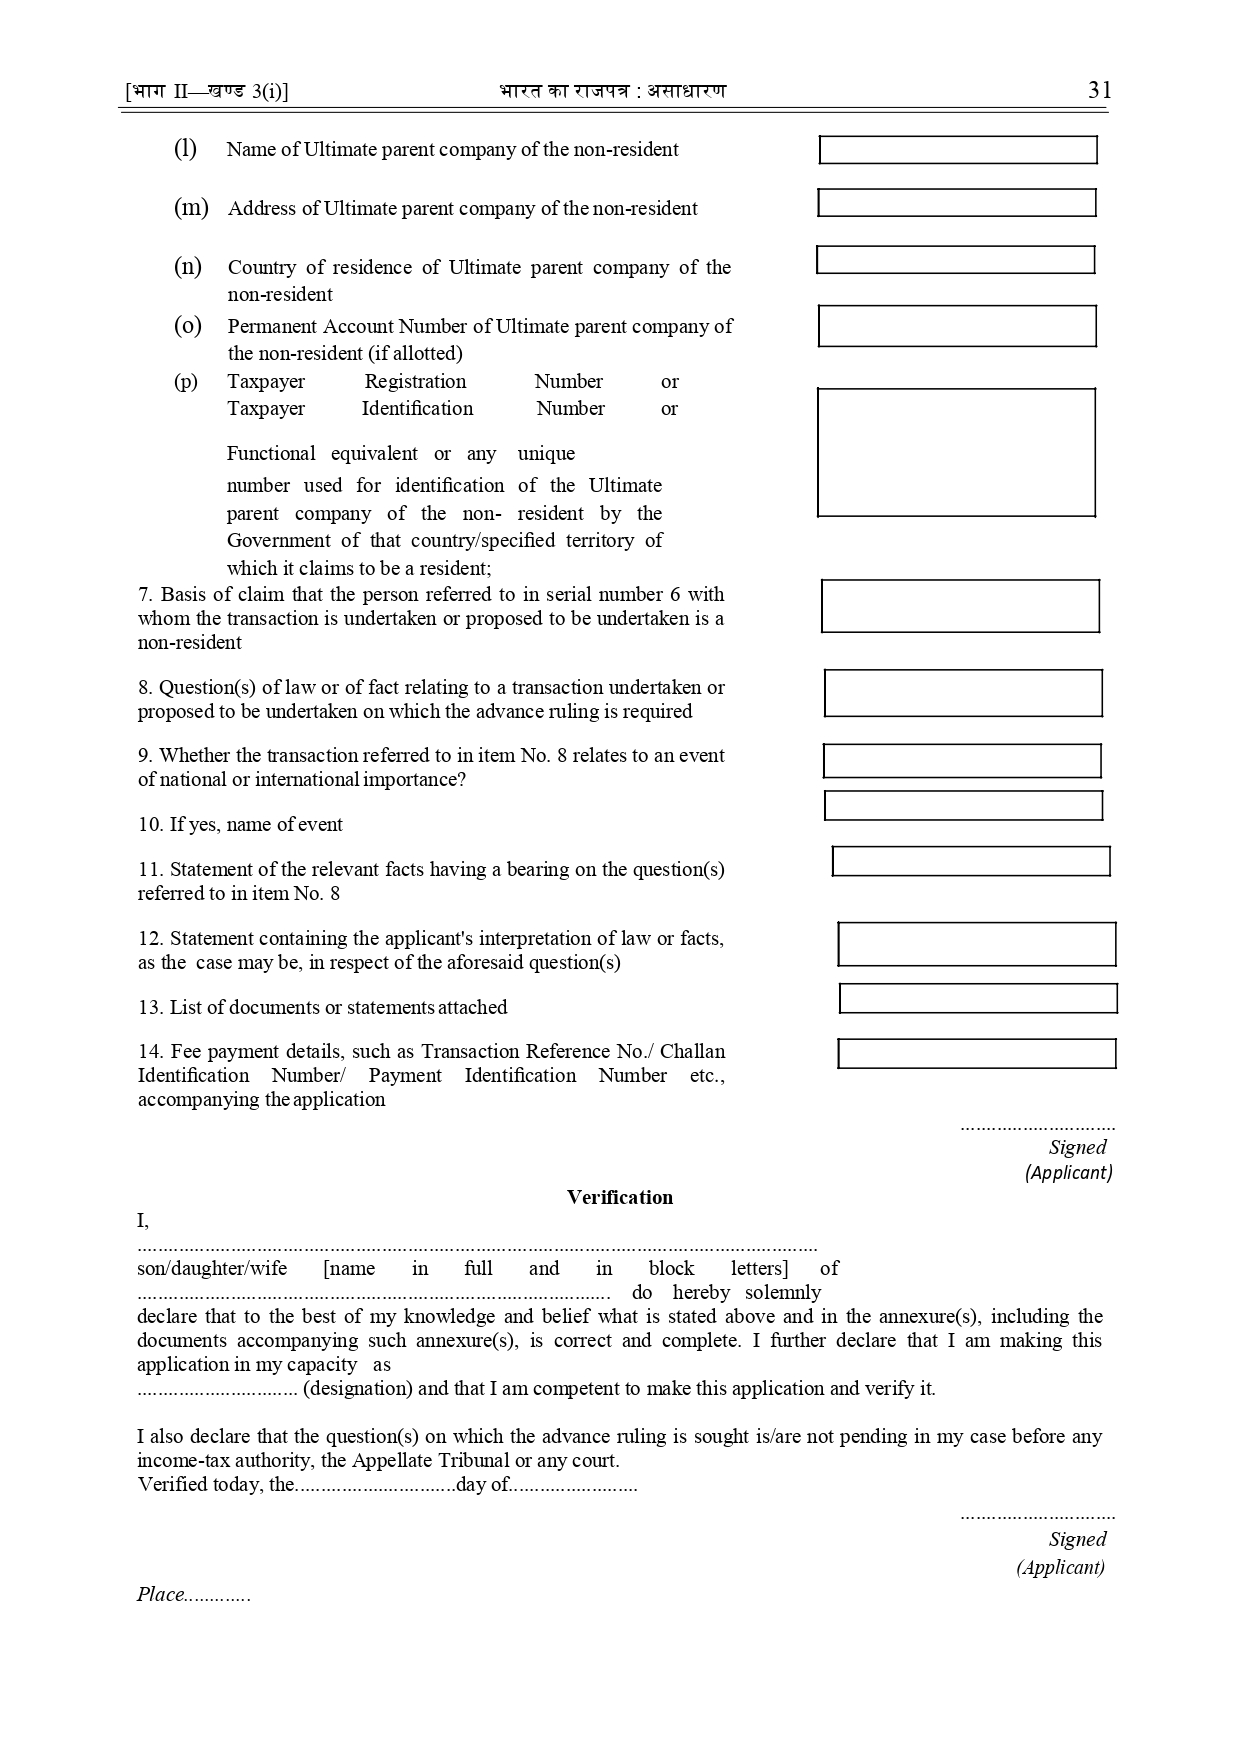
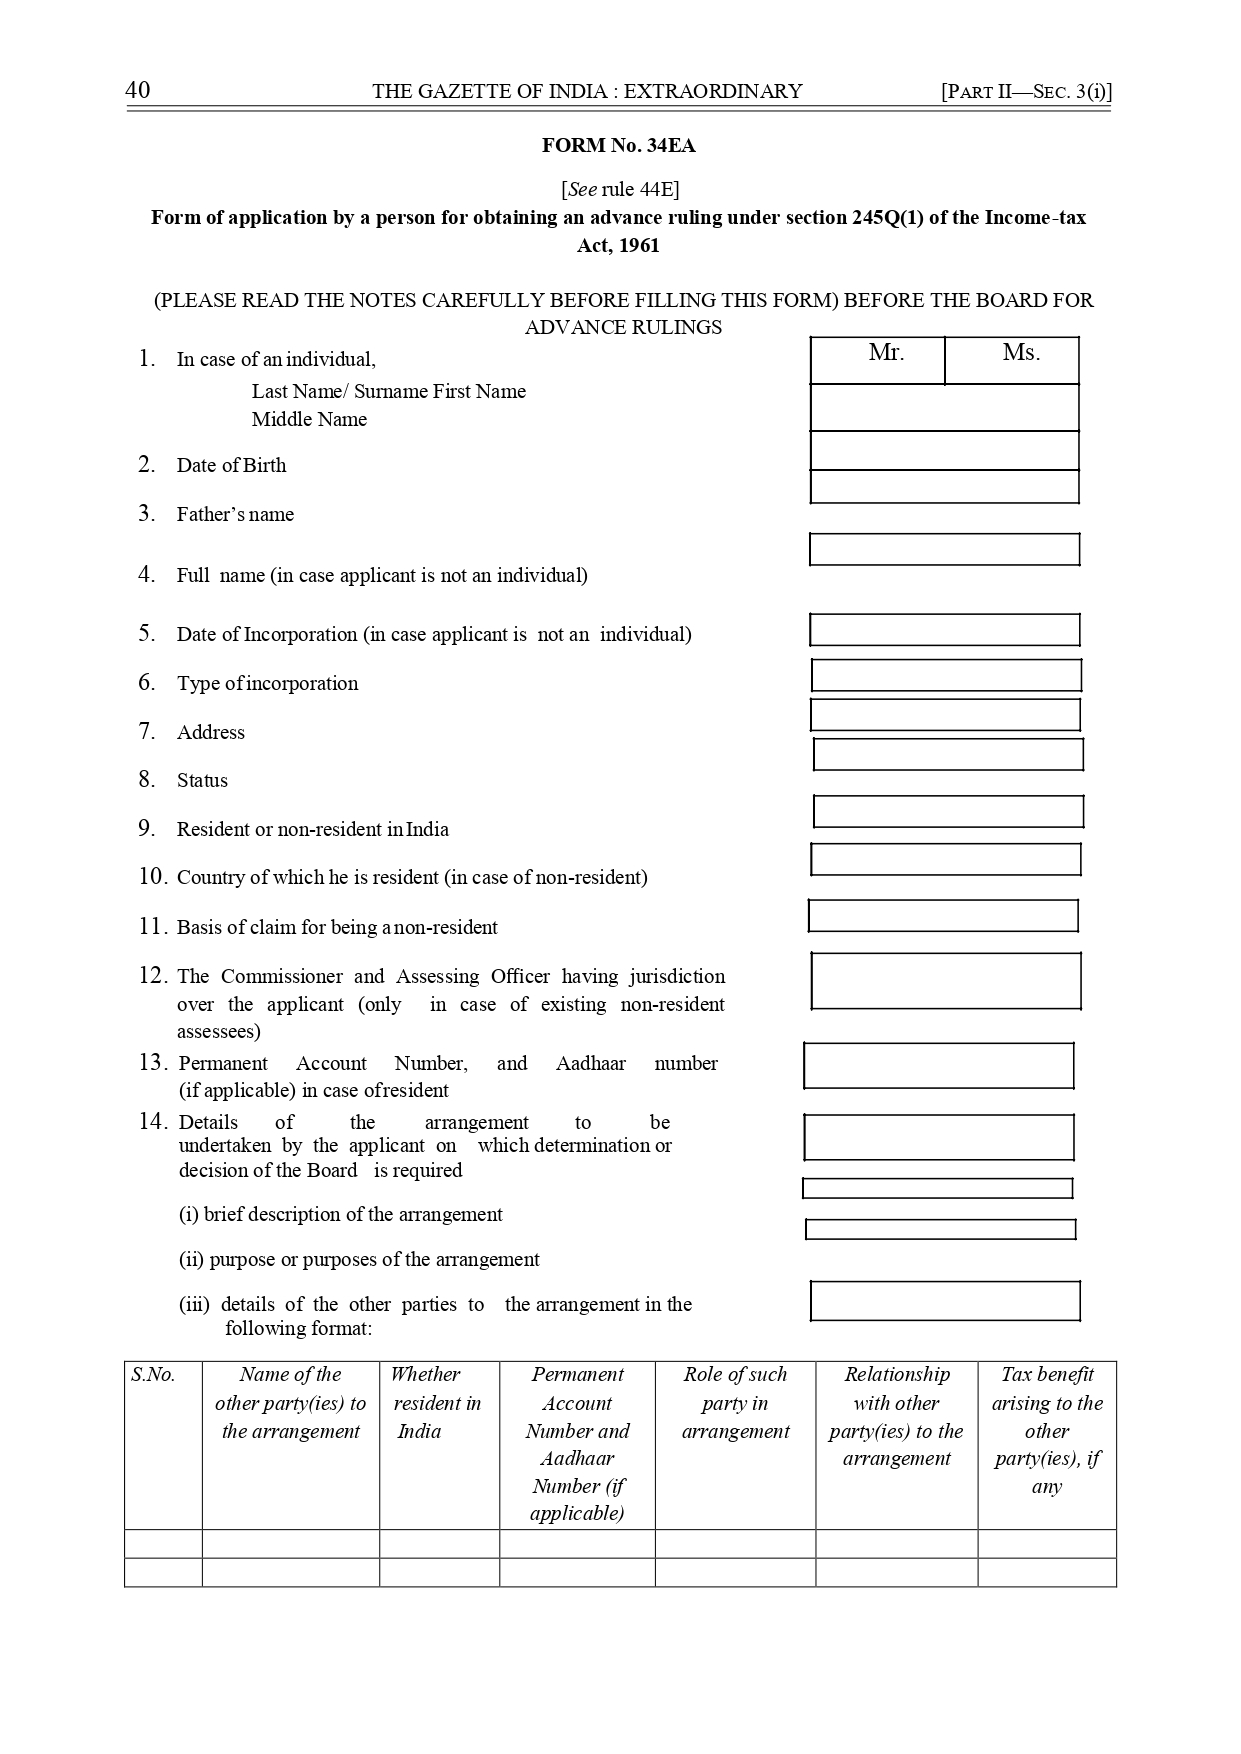
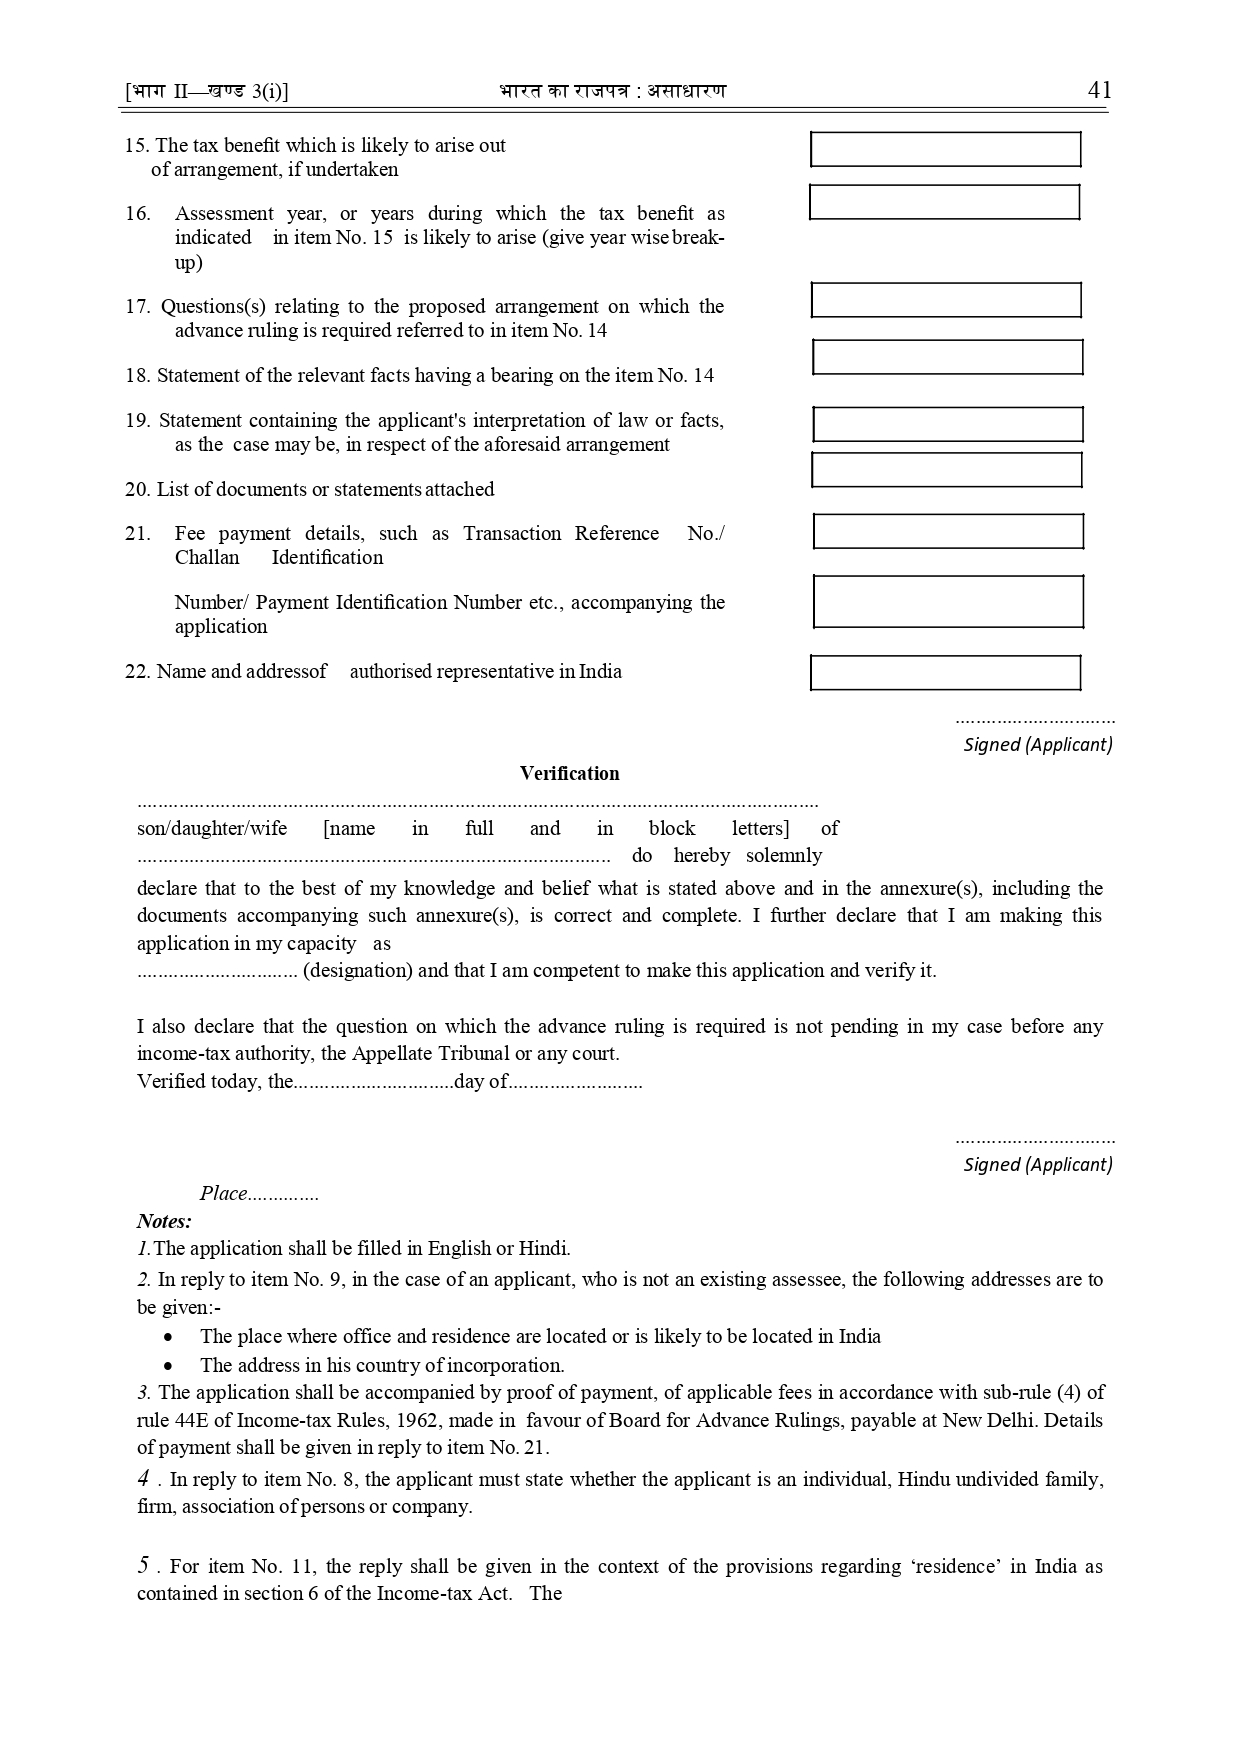
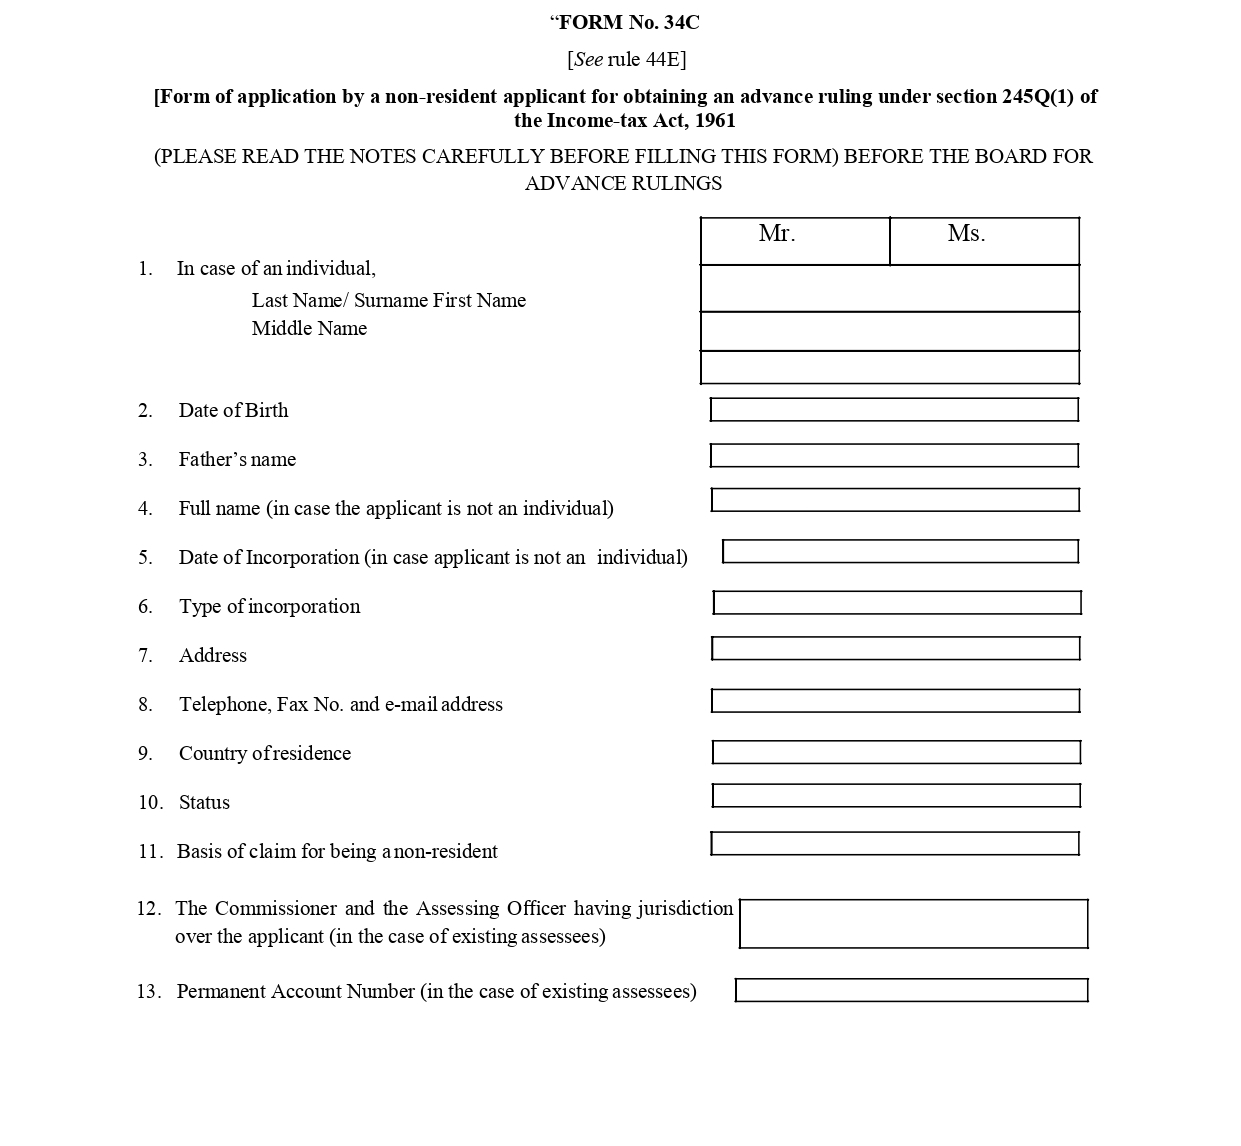
4. In the said rules, in Appendix-II, for the Forms -FORM No. 34C to FORM No. 34EA, the following Forms shall be substituted, namely:-
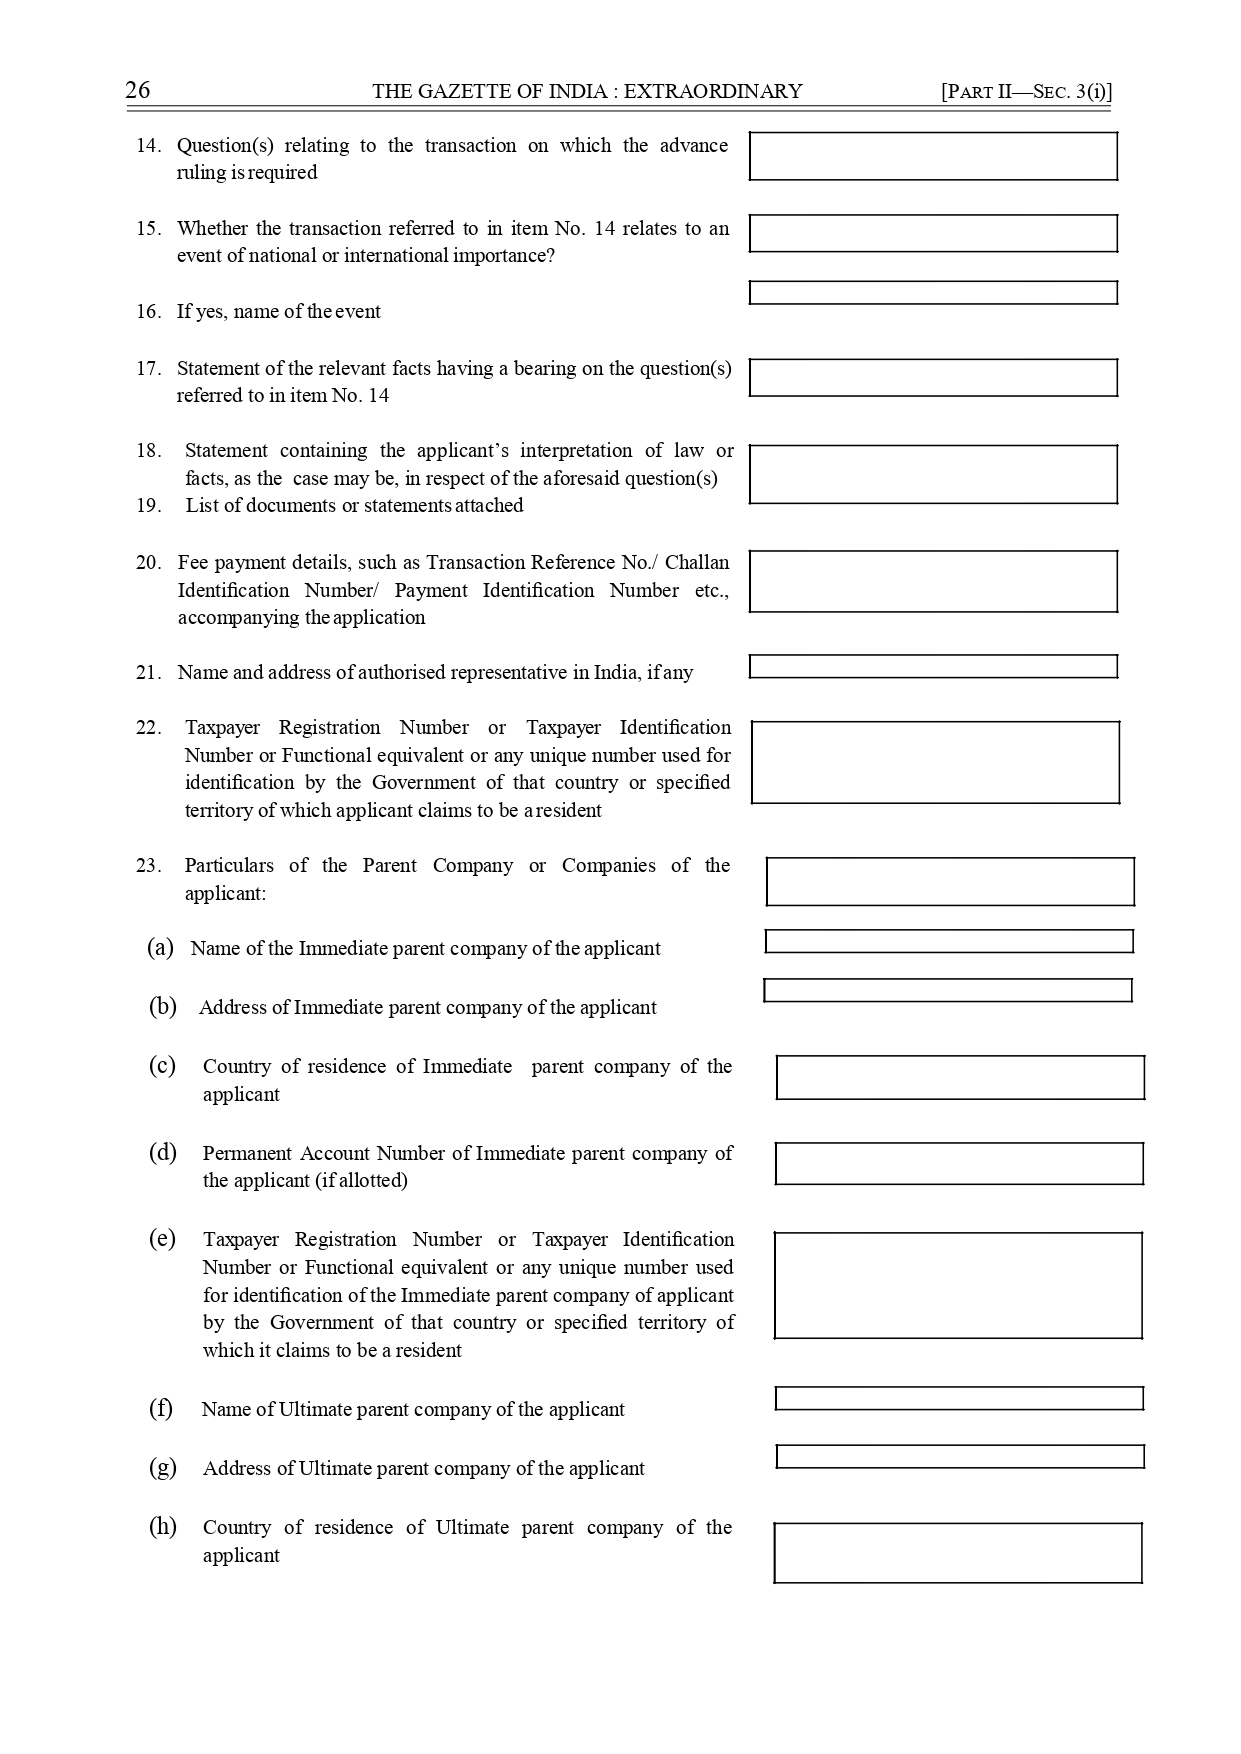
[F.No. 370142/62/2021-TPL(Part-III)]

(Prajna Paramita)
Director

Note: The principal rules were published in the Gazette of India, Extraordinary, Part-II Section-3, Sub-Section (ii) vide number S.O. 969(E) dated the 26th March, 1962 and were last amended vide notification No. G.S.R. 403 (E), dated the 31st May, 2023.


INTL TAXATION INTL MISC TP FDI LIBRARY VISA BIPA NRI TII
  • DTAA
  • Circulars (I-T Act, 1922)
  • Limited Treaties
  • Other Treaties
  • TIEAs
  • Notifications
  • Circulars
  • Relevant Sections of I-T Rules,1962
  • Instructions
  • Administrative Orders
  • DRP Panel
  • I-T Act, 1961
  • MLI
  • Relevant Portion of I-T Act,1922
  • GAAR
  • MAP
  • OECD Conventions
  • Draft Guidelines
  • DTC Bill
  • Committee Reports
  • FATCA
  • Intl-Taxation
  • Finance Acts
  • Manual on EoI
  • UN Model Taxation
  • Miscellaneous
  • Cost Inflation Index
  • Union Budget
  • Information Security Guidelines
  • APA Annual Report
  • APA Rules
  • Miscellaneous
  • Relevant Sections of Act
  • Instructions
  • Circulars
  • Notifications
  • Draft Notifications
  • Forms
  • TP Rules
  • APA FAQ
  • UN Manual on TP
  • Safe Harbour Rules
  • US Transfer Pricing
  • FEMA Act
  • Exchange Manual
  • Fema Notifications
  • Master Circulars
  • Press Notes
  • Rules
  • FDI Circulars
  • RBI Circulars
  • Reports
  • FDI Approved
  • RBI Other Notifications
  • FIPB Review
  • FEO Act
  • INTELLECTUAL PROPERTY
  • CBR Act
  • NBFC Report
  • Black Money Act
  • PMLA Instruction
  • PMLA Bill
  • FM Budget Speeches
  • Multimodal Transportation
  • Vienna Convention
  • EXIM Bank LoC
  • Manufacturing Policy
  • FTDR Act, 1992
  • White Paper on Black Money
  • Posting Policy
  • PMLA Cases
  • Transfer of Property
  • MCA Circular
  • Limitation Act
  • Type of Visa
  • SSAs
  • EPFO
  • Acts
  • FAQs
  • Rules
  • Guidelines
  • Tourist Visa
  • Notifications
  • Arbitration
  • Model Text
  • Agreements
  • Relevant Portion of I-T Act
  • I-T Rules, 1962
  • Circulars
  • MISC
  • Notification
  • About Us
  • Contact Us
  •  
     
    A Taxindiaonline Website. Copyright © 2010-2025 | Privacy Policy | Taxindiainternational.com Pvt. Ltd. OPC All rights reserved.